
Zero-Rate VAT on Aid and Humanitarian Shipments Outside the EU: Updated Tax Authority Guidance
Lithuania's STI updated its guidance on Article 50 of the VAT Law, clarifying 0% VAT rules, self-invoicing, and deduction procedures for aid sent outside the EU.
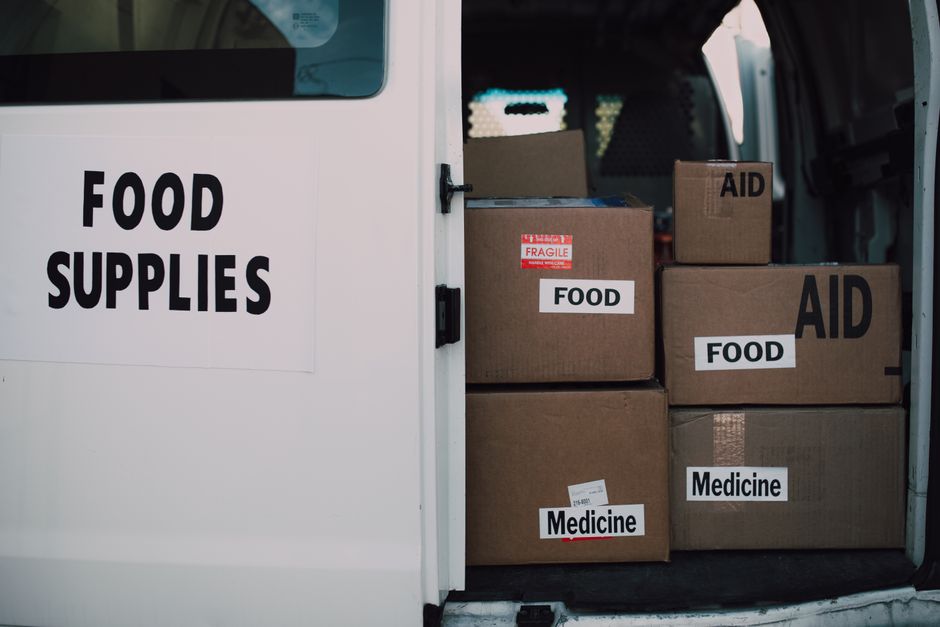
On 22 October 2026, the State Tax Inspectorate (VMI) issued letter No. (18.2-31-2 Mr) RTD-132, updating its official commentary on Article 50 of the Republic of Lithuania Law on Value Added Tax. This revision aligns administrative guidelines with statutory amendments (Law No. XV-366), extending the application of the 0% VAT rate to humanitarian aid supplied under Article 11 of the Law on Development Cooperation and Humanitarian Aid, alongside entities covered by the Law on Charity and Sponsorship.
The 0% VAT rate applies to goods physically transported outside the European Union and transferred free of charge to eligible foreign recipients of aid or humanitarian assistance. Pursuant to Article 50(3) of the VAT Law, a strict deduction-priority principle applies: registered VAT payers must recover input or import VAT through their regular VAT return. The separate VAT refund mechanism, established by the Minister of Finance, is reserved exclusively for instances where deduction is not possible, such as non-VAT payers filing refund claims via the "Mano VMI" system.
Where a taxable person donates own goods or fixed assets for which input VAT was previously deducted, Article 5 of the VAT Law deems this transfer a supply of goods for private needs, taxable at the 0% VAT rate. The business issues a self-invoice applying 0% VAT with classifier code PVM28, declaring the taxable value in box 14 of the FR0600 VAT return.
Conversely, if the transferred assets had restricted input VAT deduction under Article 62(2)(3) of the VAT Law (such as certain passenger vehicles), no taxable supply arises; no invoice is issued, and the operation is not reported on form FR0600. To support the 0% rate, taxable persons must hold a customs export declaration verifying physical exit from the EU territory and a handover-acceptance certificate signed by the recipient. When supplying goods under the Law on Development Cooperation and Humanitarian Aid, entities must also secure formal approval of the aid's expediency from the competent authority.
UAB Centro apskaita
October 29, 2026